The Short Answer
Indiana homeowners policies typically cover sudden storm damage — hail and wind — but not wear, age or deferred maintenance. Whether you receive full replacement cost depends on your policy type: RCV (replacement cost value) pays the full cost to replace less your deductible, generally in two payments; ACV (actual cash value) pays depreciated value only. Many policies also carry a separate, higher wind/hail deductible. John Beal Roofing provides free documented inspections with photographs. We do not negotiate claims and we never absorb deductibles. Call (317) 726-6000.
What Is and Is Not Covered
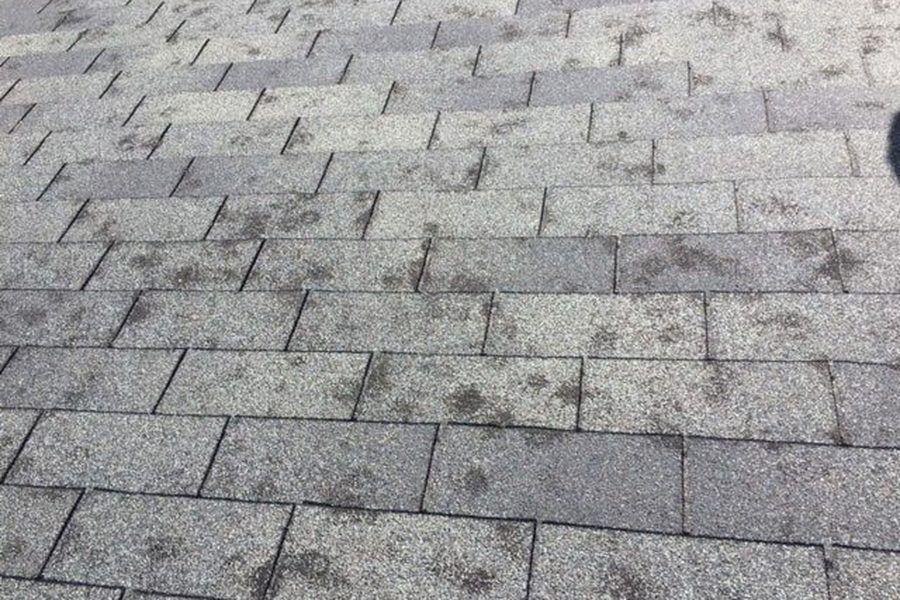
Covered, generally: sudden and accidental damage from an identifiable event. Hail impact that fractures the shingle mat. Wind that removes shingles or breaks sealant bond. A tree or limb strike. Damage to interior finishes caused by the resulting water intrusion.
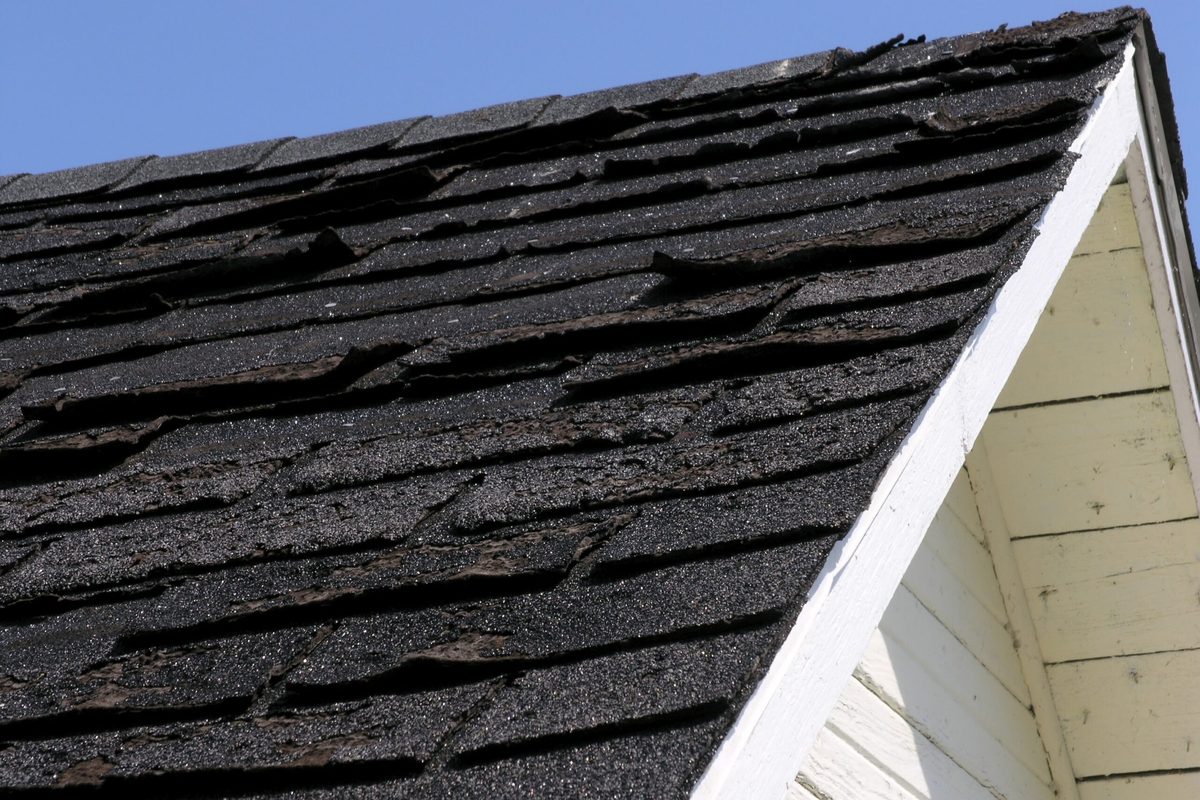
Not covered, generally: normal wear and aging, granule loss from ordinary weathering, damage attributable to poor original installation, and damage that developed gradually because a known problem was not addressed. Insurers describe this last category as maintenance, and it is the most common denial reason.
The practical implication is timing. A roof that was already at the end of its life when hail hit is a harder claim than the same event on a ten-year-old roof, and waiting a year to file makes attributing damage to a specific storm considerably harder.
ACV vs RCV: The Difference That Matters Most
RCV policies pay what it actually costs to replace the roof, less your deductible. Payment typically arrives in two parts: an initial actual-cash-value check up front, and the recoverable depreciation released after the work is completed and documented. That second check is why keeping the final invoice matters.
ACV policies pay only the depreciated value of a roof of that age. On a twenty-year-old roof that can be a small fraction of the replacement cost, leaving the homeowner covering most of the job. Many people do not know which type they hold until they file.
It is worth reading your declarations page now rather than after a storm. Also check for a separate wind/hail deductible — frequently a percentage of the dwelling coverage rather than a flat amount, and often substantially higher than the standard deductible.
The Deductible Rule, Stated Plainly
Your deductible is your obligation. A contractor who offers to waive it, absorb it, discount the job by exactly that amount, or 'work with you on it' is proposing insurance fraud. In Indiana, as elsewhere, homeowners have been prosecuted alongside contractors for these arrangements.
Treat the offer as diagnostic. A company willing to defraud an insurer on your behalf is telling you exactly how much its written warranty is worth.
We never do this. We tell people up front, and it costs us jobs to contractors who will. That has been the position since 1947 and it is not negotiable.
What We Do and Do Not Do
We do: inspect thoroughly, document with photographs, provide a written scope of the work the roof actually requires, and meet an adjuster on site to show what we found.
We do not: negotiate the claim on your behalf, advise you to file when the damage does not warrant it, inflate a scope, or touch your deductible. A denied claim can still appear in your claims history, which is a real cost of filing on cosmetic damage.
If your roof has cosmetic marking and no functional damage, our written finding will say so, and you can make an informed decision from there rather than from a sales pitch.
Frequently Asked Questions
Does homeowners insurance cover roof replacement in Indiana?
Sudden storm damage from hail or wind is typically covered. Wear, age and deferred maintenance are not. Whether you get full replacement cost depends on whether you hold an RCV or ACV policy.
What is the difference between ACV and RCV?
RCV pays the full cost to replace, less your deductible, usually in two payments. ACV pays only depreciated value, which on an older roof can be a small fraction of the replacement cost.
Can a contractor waive my deductible?
No. It is insurance fraud and homeowners have been prosecuted alongside contractors. Any contractor offering it is telling you what else they are willing to do.
How long do I have to file after a storm in Indiana?
Policies vary and many set a limit from the date of loss. Check your declarations page, and do not delay — attributing damage to a specific storm gets harder with time.
Will filing a claim raise my rates?
It can, and a denied claim can still appear in your claims history. That is precisely why we will not tell you to file on damage that does not warrant it.
Do you meet with insurance adjusters?
We will meet an adjuster on site and show what our inspection documented. We do not negotiate the claim on your behalf.
Roofing Across the Indianapolis Metro
We serve Marion County and every surrounding county — Hamilton, Boone, Hendricks, Johnson, Hancock, Morgan, Madison, Shelby and Putnam. See the full list of cities and towns we cover →
Get a free roof inspection
No charge, no obligation, and you keep the photographs. A live person answers 24 hours a day.